Here is a Long Island household that is not wealthy in any way its neighbors would notice, owes the federal government no estate tax at all, and owes New York $721,694. Everything in it is ordinary. The arithmetic is not.
The inventory
A couple in their seventies. One of them has died; this is the second death, which is when New York collects. The estate looks like this.
| Item | Value | In the New York estate |
|---|---|---|
| The house, bought in 1989, paid off | $1,400,000 | Yes, at market value |
| His rollover IRA, from a corporate career | $2,600,000 | Yes, in full |
| Her 403(b), from the school district | $900,000 | Yes, in full |
| Joint brokerage account | $1,800,000 | Yes |
| Term life policy, owned personally | $1,000,000 | Yes, the whole death benefit |
| Condominium in Florida | $600,000 | No, subtracted |
The federal gross estate is $8,300,000. Against a 2026 federal basic exclusion of $15,000,000 per person, there is no federal estate tax and no federal return is required for that reason. Most advisers who look only at the federal number will tell this family, accurately, that they do not have an estate tax problem.
The New York taxable estate is $7,700,000, because real property and tangible personal property located outside New York State come out. The 2026 New York exclusion is $7,350,000. The New York tax is $721,694.
Where the money actually went
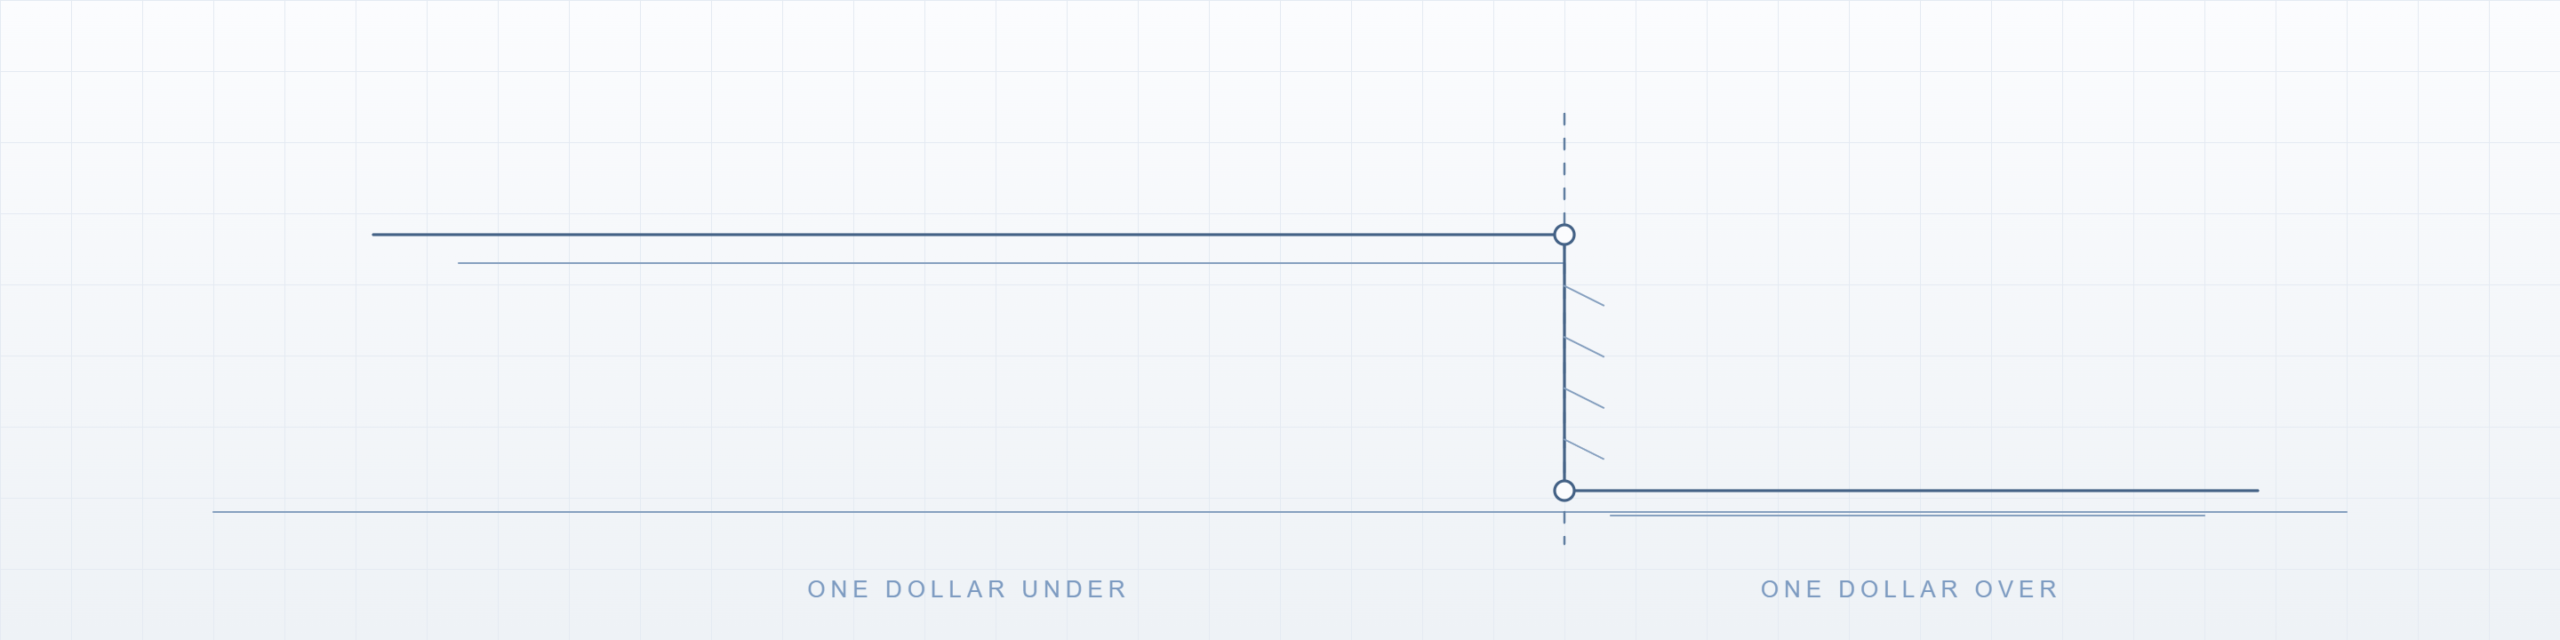
Look at what the last $350,000 of estate value cost. At $7,350,000 this family owes New York nothing. At $7,700,000 it owes $721,694. Three hundred and fifty thousand dollars of additional estate produced seven hundred and twenty-one thousand dollars of tax, an effective rate above 200%, because crossing the exclusion does not just tax the excess. It takes the exclusion away.
Now look at the term life policy. It is $1,000,000 of the estate, and it is there only because the insured owned the policy. Money that is going to a beneficiary, that never touches probate, that the family thinks of as being outside the estate entirely, is in the estate because of who held the contract. Remove that one item and the New York taxable estate is $6,700,000, which is under the exclusion, and the New York tax is nothing.
One ownership question on one insurance policy is the difference between $721,694 and zero.
The one thing this household got right without knowing it
The Florida condominium is the one piece of good news, and it is worth naming because the instinct about it is usually wrong. For a New York resident, real property and tangible personal property located outside New York State are subtracted from the New York gross estate. That $600,000 condominium would have added $93,906 of New York tax if it had been a brokerage account of the same value instead.
Intangible property does not work that way. A brokerage account, a bank account, shares in a company: these follow the owner rather than a location, and for a New York resident they stay in the New York estate wherever the institution sits. Moving the account to a Florida branch of the same bank changes nothing at all.
The part that is already lost
This is the second death. The first spouse’s New York exclusion is gone, because New York does not have portability and the first estate passed everything outright to the survivor. Federally that exclusion would have carried over. In New York it evaporated, and it was worth another $7,350,000 of shelter.
It is not fixable after the fact. It is fixed in advance, with a credit shelter trust that is actually funded, or with the New York qualified terminable interest property election, which for deaths on or after April 1, 2019 is made directly on the New York return and is irrevocable once made.
And the part that is about to be
The tax is due within nine months of death, in cash. This estate is a house, two retirement accounts, a brokerage account and an insurance payout. The insurance will cover a good deal of it, which is one of the arguments for holding insurance at all, though not for holding it in your own name.
Then there is the second tax nobody has counted. The $3,500,000 in retirement accounts is income to whoever inherits it, taxed at their rates, and a designated beneficiary who is not an eligible designated beneficiary must empty the account within ten years. Two children in their peak earning years will take that on top of their own income. The estate tax is the bill that arrives in nine months. The income tax is the one that arrives over the following decade.
Where to look
The New York estate tax page explains how the taxable estate is built, what the cliff does, and why the out-of-state rule works the way it does. The estate tax calculator will put your own figure against the exclusion for the year of death and show the marginal cost of the next $10,000. None of this is an investment question, and none of it is solved by a product: it is solved by an attorney drafting documents and by getting the titling right. If you would like to know where you stand before that conversation, start here.
Published September 13, 2026. The household is illustrative and is not a client. Figures computed with this site’s own estate tax calculator, which uses the New York rate table and the 2026 basic exclusion amount of $7,350,000. Sources: New York State Department of Taxation and Finance estate tax pages; Form ET-706 and its instructions, including Schedule B for property located outside New York State and the statement that New York does not conform to the federal portability rule; New York Tax Law section 952; IRS Revenue Procedure 2025-32, section 4.14, for the 2026 federal basic exclusion amount.
This article is general educational information and is not tax or legal advice. The New York exclusion changes every January by date of death. Estate planning decisions turn on specific facts and on how assets are titled, and they should be taken to an attorney who practices in this area.
This page is general. Your situation is not.
An estate a little over the exclusion can owe tax on the whole of it, and the fix has to be in place before death rather than after. We can cover it in a short conversation, at no charge and with no obligation.
Book your Estate Tax ReviewNot ready to book? Answer a few questions about your situation, or send a message.
Booking is handled through Rosefinch Investment Advisors. LI Retirement is not affiliated with, endorsed by, or sponsored by any government agency, retirement system, plan sponsor, or employer named on this site.