Category: Pensions

  • The service cliff in the Tier 4 teacher pension, explained

    The service cliff in the Tier 4 teacher pension, explained

    Why the NYSTRS Tier 4 formula steps up at twenty years of service, how the recalculation works, and what to verify before you choose a retirement date.

    Key takeaways

    • The NYSTRS Tier 4 formula uses a smaller fraction of final average salary per year below twenty years of service, and a larger fraction at twenty years that applies to every year, not just the new ones.
    • Service credit is not the same as years employed: part-time work, substitute service, leaves and prior public service all affect the count, and NYSTRS keeps the official record.
    • Teachers who finish at the end of a school year generally file in the spring, so the months before are the time to verify credit and request an official estimate.
    • The exact fractions, the final average salary rules and the early-retirement reduction schedule are set out in the NYSTRS Tier 4 member publications and New York Education Law, Article 11.

    Most pension formulas grow smoothly: one more year of service, one more slice of pension. The New York State Teachers’ Retirement System Tier 4 formula does not. It has a step in it at twenty years of service, and the step works backwards as well as forwards. For a Long Island teacher weighing a retirement date, that step can matter more than almost anything else in the decision.

    A formula with a step in it

    The Tier 4 benefit is built from two ingredients: your years of credited service and your final average salary. Final average salary is a defined term, an average of your highest consecutive earnings years, with limits on how much any one year can grow over the ones before it. The exact averaging period and the caps are set out in the NYSTRS Tier 4 member publications, and the underlying rules sit in New York Education Law, Article 11.

    Here is the step. With less than twenty years of credited service, the formula pays a smaller fraction of final average salary for each year of service. Once you reach twenty years, a larger fraction applies, and it applies to every year of service, not only the years after the threshold. The NYSTRS publications give the fractions themselves; what matters for planning is the shape, not the arithmetic. Crossing the line recalculates the whole career at the higher rate.

    There is a further change at 30 years, where the rate for additional years shifts again, and where the early-retirement rules also change. The Tier 4 publications set out both.

    Why the recalculation matters more than the extra year

    In a smooth formula, retiring a few months early costs a few months of accrual. At the Tier 4 cliff, retiring a few months short of twenty years means every year you ever taught is paid at the smaller fraction, for the rest of your life. The difference between nineteen-and-change and twenty is not one year of pension. It is the gap between two fractions, multiplied across an entire career, multiplied again by final average salary.

    The difference between nineteen-and-change and twenty is not one year of pension. It is the gap between two fractions, multiplied across an entire career.

    That is why this cliff appears on our pension decisions page alongside the other service credit cliffs: it is one of the places where a retirement date chosen casually, to match a lease ending or a spouse’s plans, can carry a permanent cost that nobody mentioned.

    Service credit is not the same as years employed

    The twenty years that matter are years of credited service as NYSTRS counts them, not years since your first September in a classroom. The two can diverge, and on Long Island they often do:

    • Part-time and substitute service is generally credited in proportion to the work, under rules the NYSTRS publications describe. Years that felt like full years may not count as full years.
    • Leaves of absence may or may not have earned credit, depending on the kind of leave and whether contributions continued.
    • Prior public service in New York, including service in another New York public retirement system before you joined NYSTRS, may be creditable or transferable. The system’s publications explain eligibility and what it costs to claim it.
    • Military service may be purchasable as credit under state law. Again, the publications give the conditions.

    None of this is something to estimate at the kitchen table. NYSTRS keeps the official record, publishes it to members in an annual benefit profile, and will provide an official estimate on request. If the record shows you a few months short of twenty years, the question of whether any purchasable or unclaimed service closes the gap is worth settling in writing with the system, before a retirement date is filed, not after.

    The retirement date and the school calendar

    Most Long Island teachers who retire do so at the end of a school year, and they generally file with NYSTRS in the spring. That rhythm is exactly why the cliff catches people. The natural question is which June, framed as a lifestyle choice. The prior question is what the service credit record will say on that date, because one more school year on the right side of twenty changes the formula for every year that came before it.

    A separate rule sits alongside the cliff: Tier 4 members who retire before the system’s full retirement age generally take a permanent reduction, unless they have reached the service threshold at which the reduction no longer applies. The ages and the reduction schedule are in the NYSTRS Tier 4 member publications, and they interact with the service cliff in ways that depend on your own dates. Do not rely on a colleague’s numbers; their tier, their age and their credit are not yours.

    Before you file

    Three checks, in order. First, confirm your tier: it depends on when you joined the system, and your NYSTRS benefit profile states it. Second, get the official service credit figure from NYSTRS and ask, in writing, whether any prior or purchasable service would change it. Third, request an official benefit estimate for the dates you are considering, on both sides of any threshold you are near.

    Only then does the better-known decision arrive: what payment form to take, and how to protect a spouse. That choice is permanent too, and it deserves its own attention. We cover it on the pensions page above, and the broader picture for Nassau and Suffolk educators, including the dual-pension household, on our page for Long Island teachers and NYSTRS.

    This is education, not advice. The fractions, periods, ages and schedules all live in the primary sources, and your own answer depends on your own record. Start with the record.

    Sources

    • New York State Teachers’ Retirement System (NYSTRS), Tier 4 member publications
    • New York Education Law, Article 11 (Teachers’ Retirement System)

    Important disclosures. Rosefinch Investment Advisors, Inc.
    does not provide tax or legal advice. None of the information in this article
    should be considered tax or legal advice. You should consult your tax or legal
    advisers for information concerning your own specific tax/legal situation.
    Investment advisory services offered through Beacon Global Advisor Network,
    LLC, a Registered Investment Advisor. Registration as an investment adviser
    does not imply a certain level of skill or training and does not in any way
    imply Beacon Global Advisor Network, LLC, its advisory representatives, or the
    advice and services being offered are endorsed or approved upon by any
    regulatory entity including the Securities and Exchange Commission.

    The information in this article is provided for general educational
    purposes only and does not constitute investment advice or an offer to buy or
    sell any security. All investing involves risk, including the possible loss of
    principal, and past performance does not guarantee future results. Nothing in
    this article should be interpreted as a recommendation tailored to any
    individual situation.
  • Pension or the SUNY ORP: the one-time choice at Stony Brook

    Pension or the SUNY ORP: the one-time choice at Stony Brook

    What a new Stony Brook Medicine employee gives up and gains on each side of the one-time choice between the state pension system and the SUNY Optional Retirement Program.

    Key takeaways

    • Staff in some Stony Brook titles choose a retirement plan once, within 30 days of appointment, and the choice generally cannot be changed while they work for the university.
    • The state pension promises a benefit calculated by a statutory formula, while the Optional Retirement Program promises contributions to an account whose value depends on markets.
    • Contribution rates, vesting periods and retirement ages change and depend on tier, so the current figures come from NYSLRS member publications and SUNY’s ORP information for new employees.
    • Because an ORP account generates fees for investment providers and a state pension does not, anyone paid on invested assets has an interest in which way the choice goes.

    Most retirement decisions can be revisited. You can change a savings rate, move a balance, or delay a claim. The choice some Stony Brook Medicine employees face in their first weeks on the job is different. As the Stony Brook Medicine page on this site explains, staff in some titles choose a retirement plan once, within 30 days of appointment, and the choice generally cannot be changed while they work for the university. That makes it worth understanding before the window opens, not after it closes.

    Who faces the choice, and what is on the menu

    Stony Brook Medicine staff are employed by the State University of New York, so the retirement options are set by the state, not the hospital. Which options appear on a given employee’s menu depends on the title of the appointment. SUNY’s Optional Retirement Program information for new employees describes who is eligible to elect the ORP and which state retirement systems are the alternatives for each category of title. For many hospital titles the alternative is the New York State and Local Retirement System, NYSLRS, and a new member of that system joins its current tier, Tier 6. If you are unsure which systems your title qualifies you for, that SUNY document and the campus benefits office are the places to confirm, because this article cannot know your title.

    The defined benefit path: a pension set by statute

    A defined benefit pension is a promise of an amount. The rules for NYSLRS tiers are written into the New York Retirement and Social Security Law, in Articles 14 and 15, and the benefit at retirement comes from a formula in that law: it is built from your years of credited service and an average of your earnings over a period the statute defines. The result is a monthly payment for life. It does not rise or fall with markets, and the investment risk sits with the state’s pension fund, not with you.

    The pension has conditions. Members contribute from their pay at rates set in law, and the pension only becomes yours after a minimum period of credited service, called vesting, also set in statute. Leave state service before vesting and you generally have a right to your own contributions back, not to a pension. The formulas, contribution rules, vesting periods and retirement ages differ by tier and have changed over the years, which is why this article states none of them. The NYSLRS member publications on Tiers 4, 5 and 6 give the current figures for each tier, and the site’s Tier 6 pension calculator walks through how the current formula fits together.

    The defined contribution path: the SUNY ORP

    The Optional Retirement Program is a promise of contributions, not of an amount. SUNY and the employee pay into an account held in the employee’s name with one of the investment providers SUNY authorizes, and the balance at retirement depends on what went in and how the investments performed. There is no statutory benefit formula. The account is generally portable if you leave SUNY, which matters to people who do not expect to spend a career there. It produces lifetime income only if you arrange that yourself, by a withdrawal plan or by using the balance to buy an annuity, an insurance contract that pays income for life.

    The pension promises an amount. The ORP promises contributions. Nearly everything that matters in this choice follows from that one difference.

    Contribution rates and the ORP’s own vesting rules are described in SUNY’s Optional Retirement Program information for new employees. Do not rely on a colleague’s memory of them: colleagues who joined in different years may have joined under different terms.

    What the decision actually turns on

    Stripped to its essentials, the choice is about who bears which risk, and for how long you expect to stay.

    • Who bears investment risk. In the pension, the state does. In the ORP, you do, in both directions.
    • How long you stay. The pension formula rewards long service and vesting; the ORP travels with a shorter stay.
    • Longevity. A pension pays as long as you live. An ORP balance lasts as long as the money does, unless you convert it to lifetime income.
    • The fine print. Survivor benefits, disability provisions and post-retirement adjustments work differently in each, and the details are in the statute, the NYSLRS publications and the SUNY ORP materials, not in any summary, including this one.

    One conflict of interest is worth naming plainly: an ORP account holds investments that generate fees for investment providers, and a state pension does not, so anyone who is paid on invested assets has a financial interest in which way a new employee chooses.

    Where the current rules and figures live

    This article has deliberately stated no contribution rate, vesting period, retirement age or deadline beyond the 30-day window the Stony Brook page describes, because those figures depend on tier and change over time. The current rules come from three places: the New York Retirement and Social Security Law for the statutory framework, the NYSLRS member publications for the pension tiers, and SUNY’s Optional Retirement Program information for new employees for the ORP and for eligibility by title. Your appointment letter and the campus benefits office confirm your own window. The voluntary savings plans available at Stony Brook are a separate matter from this choice, and the Stony Brook Medicine page covers them alongside the rest of the picture.

    Sources

    • New York Retirement and Social Security Law, Articles 14 and 15
    • New York State and Local Retirement System (NYSLRS), member publications on Tiers 4, 5 and 6
    • State University of New York, Optional Retirement Program information for new employees

    Important disclosures. Rosefinch Investment Advisors, Inc.
    does not provide tax or legal advice. None of the information in this article
    should be considered tax or legal advice. You should consult your tax or legal
    advisers for information concerning your own specific tax/legal situation.
    Investment advisory services offered through Beacon Global Advisor Network,
    LLC, a Registered Investment Advisor. Registration as an investment adviser
    does not imply a certain level of skill or training and does not in any way
    imply Beacon Global Advisor Network, LLC, its advisory representatives, or the
    advice and services being offered are endorsed or approved upon by any
    regulatory entity including the Securities and Exchange Commission.

    The information in this article is provided for general educational
    purposes only and does not constitute investment advice or an offer to buy or
    sell any security. All investing involves risk, including the possible loss of
    principal, and past performance does not guarantee future results. Nothing in
    this article should be interpreted as a recommendation tailored to any
    individual situation.
  • Rates went up this year. Your pension lump-sum offer probably went down

    Rates went up this year. Your pension lump-sum offer probably went down

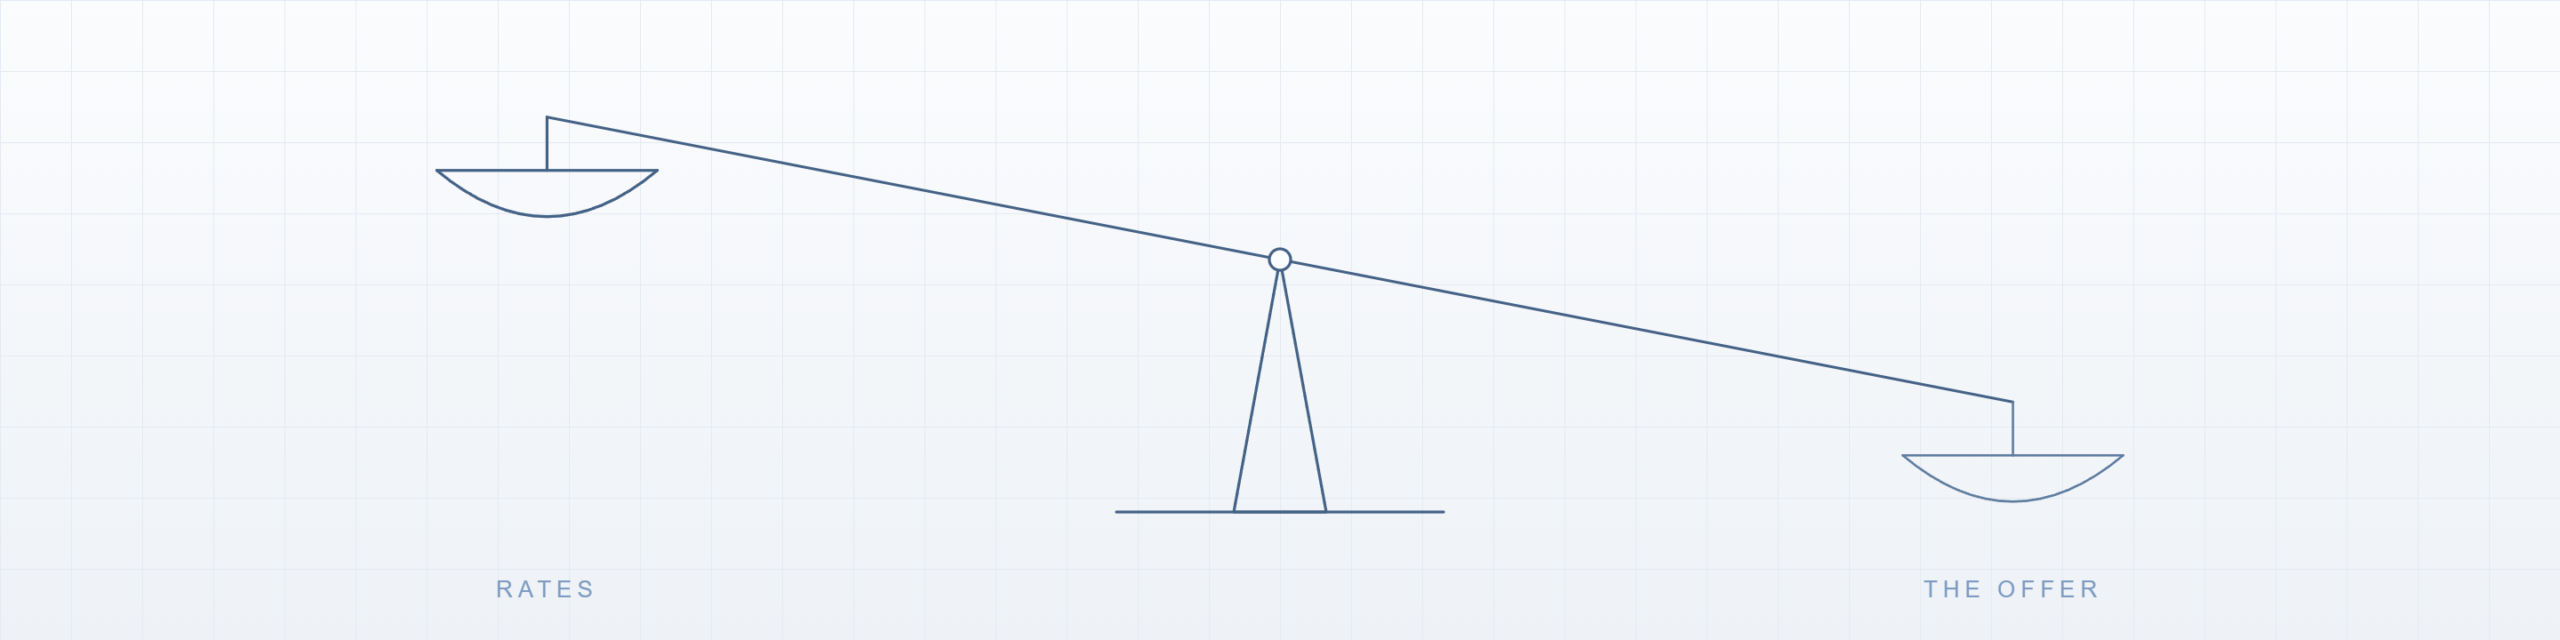
    A line drawing of a balance scale tilted so that the pan labelled rates sits high and the pan labelled the offer sits low.

    If you have a legacy pension from a corporate employer and the plan offers a lump sum instead of the monthly benefit, the size of that lump sum is not a negotiation. It is an arithmetic result of your promised monthly amount, an IRS mortality table, and three interest rates that the IRS publishes every month under section 417(e)(3) of the tax code. When those rates rise, the lump sum for the same pension falls.

    What moved

    In January 2026 the three segment rates were 4.03%, 5.20% and 6.12%. For July 2026, the most recent month published, they were 4.62%, 5.62% and 6.51%. The first rate discounts payments in the first five years, the second covers years five to twenty, and the third everything after.

    Using the IRS mortality table that applies for 2026, a $2,000 a month single-life pension starting at 65 is worth about $309,100 at the January rates and about $296,000 at the July rates, roughly 4.2% less for the identical promise. At 60 the gap is nearer 4.7%, because more of the payments sit in the later, higher-rate segments. These are illustrations from the published tables, not a quote from any plan.

    Which month your plan uses

    Plans do not use the current month. Each plan document names a lookback month and a stability period; one design fixes the lump-sum basis for a whole calendar year from the rates of a month in the prior year, for example August, October or November. That has two consequences. First, if your plan’s 2027 basis is set from a late-2026 month, the offers you see next year will reflect this year’s higher rates. Second, if you are already eligible to retire, the offer available in 2026 was set from a 2025 month, and it may be the larger of the two. The plan document states the month and the period, and the plan administrator can tell you which apply to you; ask before you rely on an offer.

    Smaller lump sum does not mean take the pension

    A lower lump sum is the same promise priced at a higher rate, so in principle the two are still equivalent. The choice turns on things the formula ignores: your health and your spouse’s, whether the plan is well funded and what the Pension Benefit Guaranty Corporation would cover if it were not, whether you need the money to be flexible or need it to be automatic, and what the lump sum would have to earn to replace the pension for as long as you both live. On the last point, the annuity calculator on the Calculators page turns a balance back into a monthly figure on the same IRS basis, so you can compare a lump sum against what it would buy.

    Who this applies to on Long Island

    This is a corporate-plan decision. NYSLRS and NYSTRS do not offer a lump sum in place of the monthly allowance; the choices there are the survivor options at retirement. Where the question does arise locally is with a legacy pension from a utility, defense, financial or telecom employer, and with hospital systems that have frozen a defined benefit plan. New York taxes a private pension above the $20,000 annual exclusion, and it taxes a rolled-over lump sum when withdrawn on the same basis.

    If an offer is on your desk

    Get the plan’s relative value disclosure, the lookback month, and the monthly benefit at your normal retirement age, then compare the offer to what the same monthly amount costs on the open market. If you would like that comparison run with you, start here.


    Reviewed September 12, 2026. Sources: IRS Notice 2026-51 (July 2026 segment rates, Internal Revenue Bulletin 2026-38); IRS minimum present value segment rates table; IRS Notice 2025-40 (applicable mortality table for 2026); Internal Revenue Code section 417(e)(3).

    This article is general educational information and is not investment or tax advice. The illustrations use published IRS tables and are not a quote from any plan; your plan’s own basis, lookback month and benefit formula govern. Confirm figures with your plan administrator before deciding.

    Several of these choices cannot be undone.

    A lump sum offer is priced off rates that move month to month, and the election is permanent once made. We can cover it in a short conversation, at no charge and with no obligation.

    Book your Pension ReviewNot ready to book? Answer a few questions about your situation, or send a message.

    Booking is handled through Rosefinch Investment Advisors. LI Retirement is not affiliated with, endorsed by, or sponsored by any government agency, retirement system, plan sponsor, or employer named on this site.

  • Retiring from NYSLRS in 2027? The application window is 15 to 90 days, and the option deadline is tighter than you think

    Retiring from NYSLRS in 2027? The application window is 15 to 90 days, and the option deadline is tighter than you think

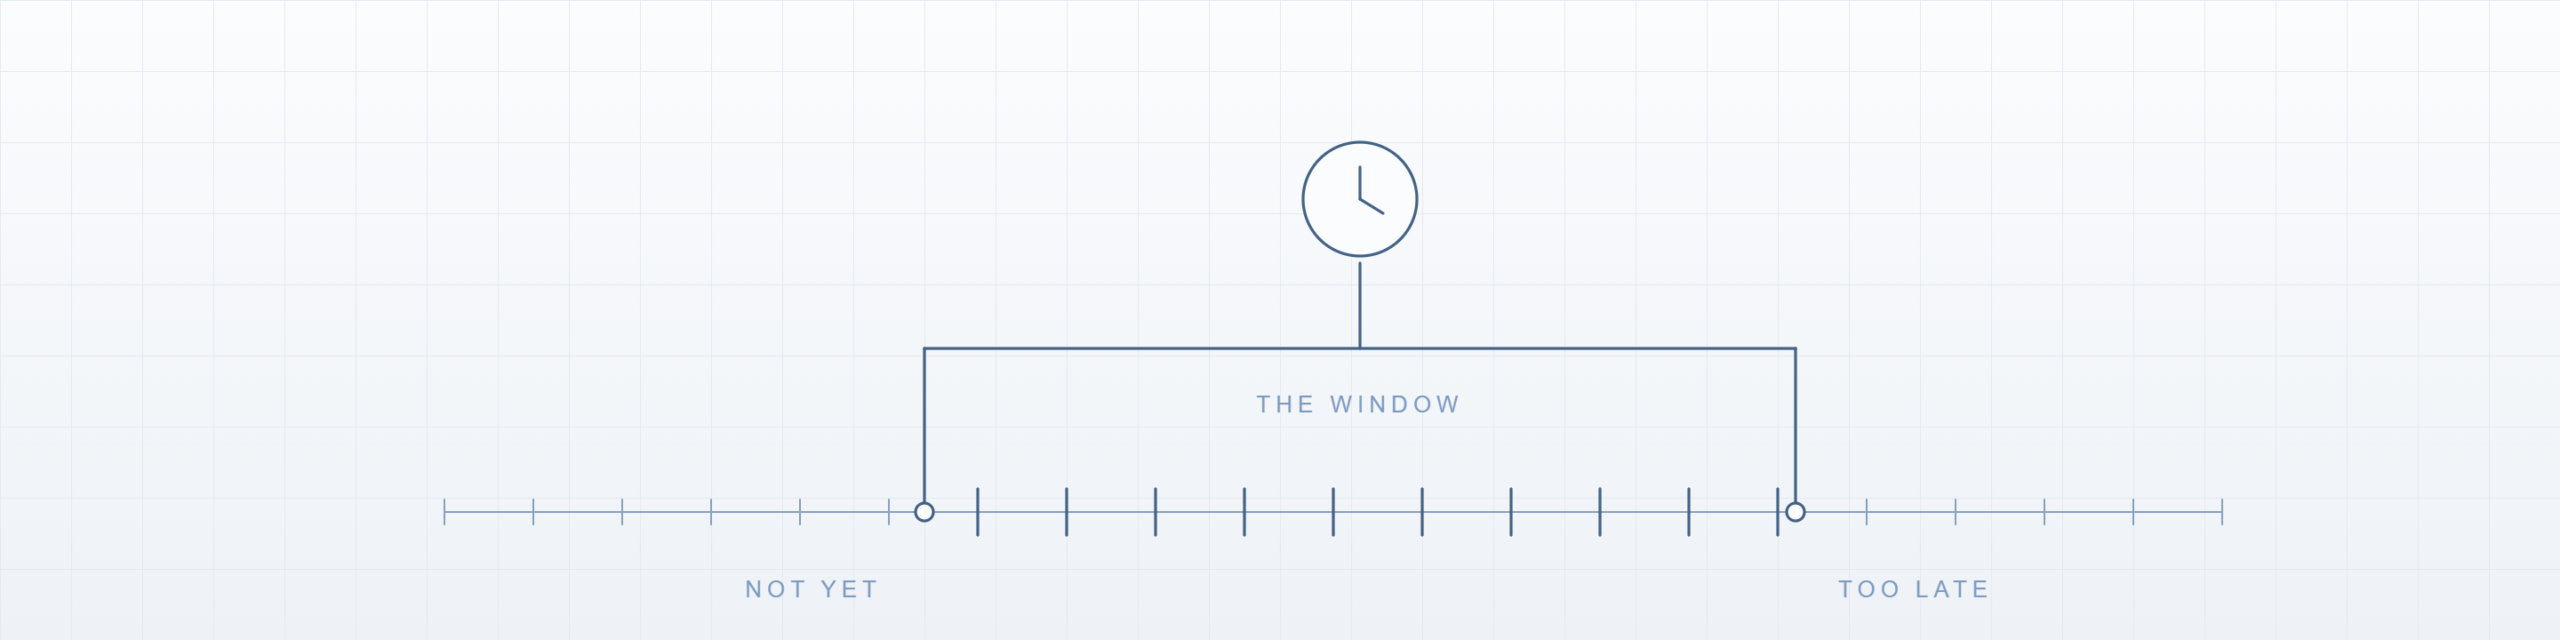
    A line drawing of a timeline with a bracketed window in the middle and a clock above it, labelled not yet, the window, and too late.

    If you plan to retire from a Nassau or Suffolk county job, a town or village, or state service in 2027, the application itself is a short window inside a long decision. The Office of the State Comptroller publishes the rules, and the dates are firm. Teachers in NYSTRS follow a separate process with its own deadlines, which is not covered here.

    When to file

    You must apply at least 15 days and no more than 90 days before your retirement date. The application is filed in Retirement Online or on form RS 6037, which must be notarized. Filing early is not possible; an application received more than 90 days ahead will not be accepted. Filing late moves the date.

    Your retirement date can be any day, including a weekend or a holiday, so if your last day of work is a Friday your retirement date can be the Saturday. That flexibility matters for the final average earnings calculation and for service credit, and for a member below normal retirement age in a tier with an age reduction, a date a few weeks later can change the reduction. The pension estimator on the Calculators page shows the effect of the date; Retirement Online’s Estimate My Pension Benefit tool does it from the actual record and should be run first.

    What to have ready

    • Proof of date of birth. No benefit is paid until NYSLRS has it. A birth certificate, passport, driver’s license, marriage certificate, baptismal certificate, DD-214 or naturalization papers are accepted.
    • Your beneficiary and option decision. The payment option governs what a survivor receives, and the deadline to change it is short.
    • The estimate from Retirement Online, which uses your actual service and earnings.

    The option deadline

    For most members the pension payment option must be selected by the end of the month in which you retire. Once selected, you have 30 days after the first day of the following month to change it. Members of ERS Tiers 4, 5 and 6 under Article 15 must select by the retirement date itself. After the window closes the option is final, whatever your circumstances later become. Decide the option before you file, not after the first payment.

    What happens to the money

    For most members the first pension payment arrives at the end of the month following the month you retire, so a retirement in late January is first paid at the end of February. Plan for one month of bridging cash. The NYSLRS pension is exempt from New York State income tax in full; it is federally taxable, and the first retirement year, with final salary and a first pension in the same year, is often the highest-income year in the sequence and the one that sets the Medicare premium two years on. The county employees and teachers pages cover the tier rules in full.

    A working timeline

    Twelve months out, run the Retirement Online estimate and settle the date. Ninety days out, the window opens; file with proof of date of birth. Fifteen days out, it closes. By the end of the retirement month, the option is chosen; thirty days after the first of the next month, it is final. If you would like to walk through the option choice before filing, start here.


    Reviewed September 12, 2026. Sources: Office of the New York State Comptroller, Preparing and Applying for Retirement (rev. August 2025); Application for Service Retirement, form RS 6037.

    This article is general educational information and is not advice about your retirement application. Filing windows, deadlines and option terms are set by the Retirement System and can change. Confirm your own dates with NYSLRS and your employer before filing.

    Several of these choices cannot be undone.

    The filing date sets the payment start, and the option election that goes with it cannot be changed afterwards. We can cover it in a short conversation, at no charge and with no obligation.

    Book your Pension ReviewNot ready to book? Answer a few questions about your situation, or send a message.

    Booking is handled through Rosefinch Investment Advisors. LI Retirement is not affiliated with, endorsed by, or sponsored by any government agency, retirement system, plan sponsor, or employer named on this site.